


Pendle's Ambition: Capturing All Yield from Stablecoins, RWAs, and Perpetuals
 Blockbeats
Three potentially game-changing directions where Pendle has already positioned itself
Yield is one of the oldest tools in finance.
It is the gravity around which money orbits, determining the flow of every dollar in the financial system. Yield is the spice that governs the financial universe, and Pendle's plan is to become the black hole that sucks in all of it.
A black hole is a celestial body with gravity so strong that not even light can escape its pull.
Pendle V2 and Boros together form a system designed to attract every form of yield in the world.
V2 captures all yield embedded in on-chain tokens, while Boros covers the rest, including the funding rates in perpetual futures markets that see hundreds of billions of dollars change hands annually.
After five years of building, Pendle has evolved from a protocol of a few scattered pools into the fixed-income and interest-rate base layer of DeFi.
Today, it has sufficient liquidity, ecosystem integrations, and cross-chain connectivity to allow any yield in crypto markets to be seamlessly priced and locked into fixed income.
Boros fills another gap that no one had truly solved before: providing a market where funding rates can be fully traded and monetized.
As the infrastructure matures, we are confident that three crypto sector themes in this cycle will become high-growth, even game-changing directions, and Pendle has already positioned itself to capture these incoming waves:
· Stablecoins
· Tokenized RWAs
· Perpetual futures
Wave One: Stablecoins
Stablecoins never go out of style.
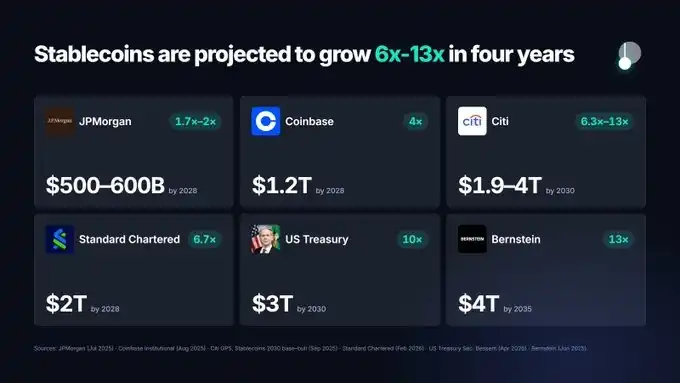
Most industry leaders and institutions expect the stablecoin market to grow significantly, and banks and payment networks are preparing to enter this market.
As of mid-September 2026, total stablecoin supply is approximately $300 billion, up 14% year over year.
Citi's base-case forecast for the stablecoin market by 2030 is $1.9 trillion, while Standard Chartered expects it to reach $2 trillion by 2028—about six times the current level.
Regulatory frameworks have also begun to take shape.
USDG, launched by Paxos, is backed by the Global Dollar Network alliance, whose members include Kraken, Robinhood, Galaxy, and Mastercard.
USDG has already established markets on Pendle and has performed very well.
Earlier this year, Pendle briefly became the largest USDG holder on Ethereum, accounting for 27.9% of total supply.
Less than two months after USDG launched on Pendle, its size on Pendle grew from zero to $121 million.
On X Layer, Pendle's USDG market alone accounts for 40% of the entire chain's TVL.
Stablecoins have always been one of Pendle's core businesses.
For stablecoin issuers, simply integrating with the Pendle ecosystem provides significant product utility and distribution capabilities.
This year, stablecoin pools on Pendle have generated $6 billion in notional trading volume.
And this is not the first time this has happened.
At its peak, about half of Ethena's TVL—nearly $7 billion—was on Pendle.
This year on Monad, TVL in AUSD-related markets alone reached about $230 million, and Pendle at one point accounted for more than 78% of total AUSD supply.
This pattern has repeated so often that Dune has given it a name: the "Pendle Effect," defined as "the surge in demand a token experiences after Pendle Finance launches PT/YT markets for it."
As the stablecoin wave expands, Pendle will grow with it.
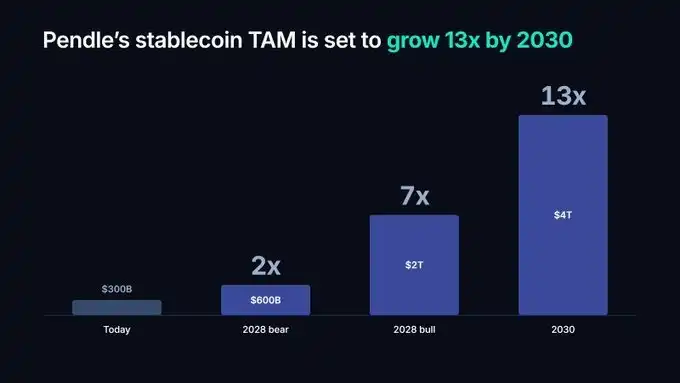
Even under JPMorgan's most pessimistic forecast, if stablecoin supply merely doubles, Pendle's addressable stablecoin market will still double over the next year and a half and grow tenfold within four years.
Wave Two: Tokenized RWAs
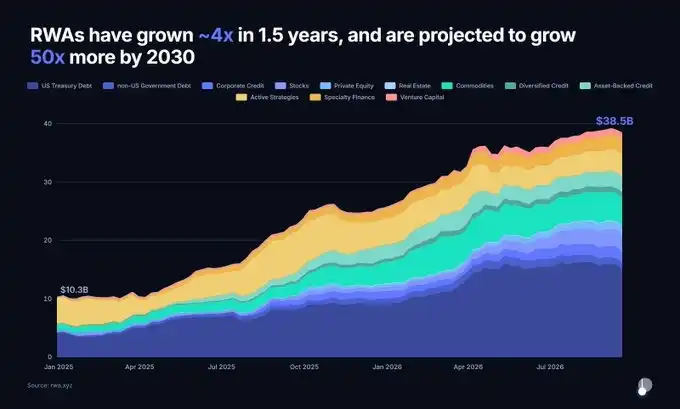
Excluding stablecoins, the size of tokenized real-world assets (RWAs) has grown from about $10 billion at the start of 2025 to nearly $39 billion today.
In less than two years, the market has grown nearly fourfold.
Among these, U.S. Treasuries, private credit, commodities, and tokenized equities have each surpassed $1 billion in size.
Market forecasts for RWA size by 2030 vary widely.
Conservative estimates are around $2 trillion, while more optimistic projections exceed $16 trillion.
Even the most cautious forecast implies this market will grow about 50x in less than four years.
RWAs have become one of Pendle's most important development priorities in 2026.
Of the markets launched on Pendle this year, 66 are RWA-related, covering U.S. Treasury bills, private credit, STRC dividends, tokenized equities, and compute infrastructure assets.
We have also helped these markets attract substantial asset size and user activity.
Currently, $210 million worth of RWA-backed PTs are being used as collateral on Morpho.
In May this year, TVL in Pendle's STRC market briefly exceeded $500 million, with cumulative trading volume surpassing $977 million, making it the primary source of activity in the entire ecosystem.
USDai tokenizes compute infrastructure.
Earlier this year, its TVL on Pendle peaked at $568 million, with total trading volume of about $2.5 billion.
A fund under Partners Group recently went live on Pendle.
This means the investment strategies of this well-known private equity firm, which manages $185 billion, have officially entered the Pendle ecosystem, opening another potentially massive channel for asset inflows.
Despite Pendle's achievements, we believe we are still in the very early stages.
Robinhood's recent innovations have shown that seamless tokenization is just beginning to demonstrate product-market fit, and the line between on-chain and off-chain is rapidly blurring.
We expect that when this wave fully unfolds, it will have a structural impact on the entire industry.
As the RWA wave expands, Pendle will grow with it.
As a side note: in the coming weeks, we will announce a new technical innovation that allows assets with no yield to be split into PT/YT in a way more suitable for degen users.
Stay tuned.
Wave Three: Perpetual Futures
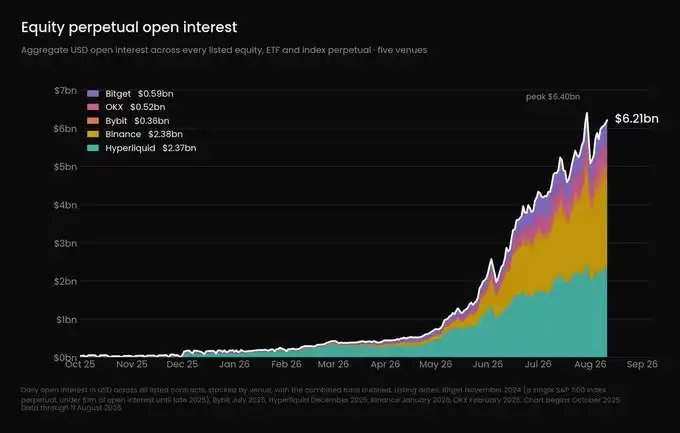
Source: https://ethena.fi/blog/extending-the-basis-trade-to-equities
Ethena's conclusion is that perpetual futures tied to equities and commodities are among the few opportunities in crypto that still have 100x growth potential.
We agree with that assessment.
Currently, open interest in equity perpetuals has surpassed about $6 billion, growing more than 10x in six months.
This year, trading volume in equity-related products on Hyperliquid has grown from $4 billion to $212 billion.
When SpaceX went public, price discovery occurred in the perpetual futures market even before the stock officially began trading.
ICE, the parent company of the New York Stock Exchange, has taken a stake in OKX and introduced its Brent and WTI benchmarks to OKX's perpetual futures market.
Kalshi has also launched the first CFTC-regulated perpetual futures in the United States.
Perpetual futures are rapidly becoming the de facto 24/7 trading market for all asset classes.
And the funding rates generated in this process have become too significant to ignore.
As Ethena pointed out, these perpetuals have consistently carried very high funding rates.
In May this year, the open-interest-weighted average funding rate on Hyperliquid annualized to 14%, while Binance's average reached 17.5%.
The volatility of crude oil perpetual funding rates is 14 times that of BTC funding rates.
On 40% of trading days, crude oil funding rates flip between positive and negative.
From April 6 to April 14, oil prices fell from $113 to $91.
Even with a perfectly correct short direction, shorts still paid out significant profits in funding fees.
Faced with such high volatility, Boros offers the ability to lock in funding costs.
Users can build fixed-income carry trades or simply bet on whether funding rates will rise or fall.
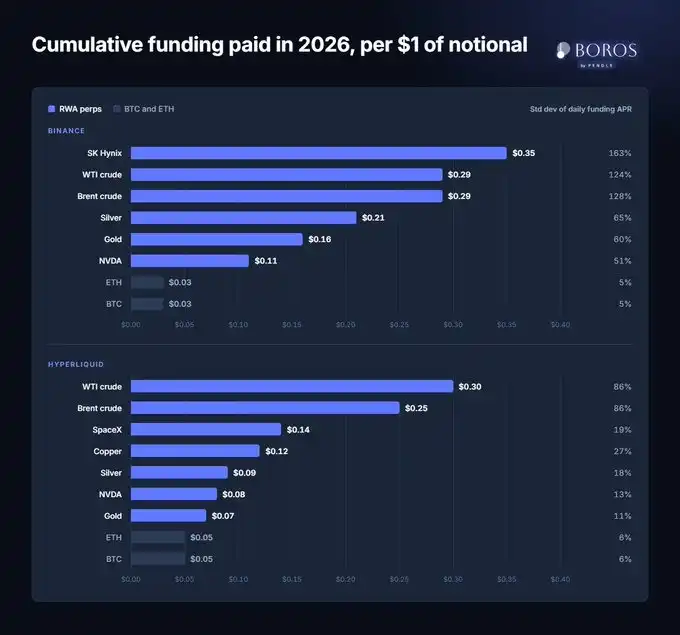
This year on Binance, holding $1 notional of BTC perpetuals costs about $0.03 in funding fees.
But holding SK Hynix perpetuals costs as much as $0.35.
The standard deviation of BTC daily funding rates is about 5%.
Gold and silver reach 60% to 65%, and SK Hynix is as high as 163%.
RWA funding rates are completely different from anything we have seen before.
No trading desk or trader can maintain a highly leveraged position long-term while absorbing such violently fluctuating holding costs.
Every new RWA perpetual listed creates a new set of funding costs.
And funding rates across different trading platforms are almost never neatly aligned.
By partnering with prime brokers like CrossEx, Boros has helped users execute these arbitrages and relatively easily achieve annualized returns of 30% to 40%.
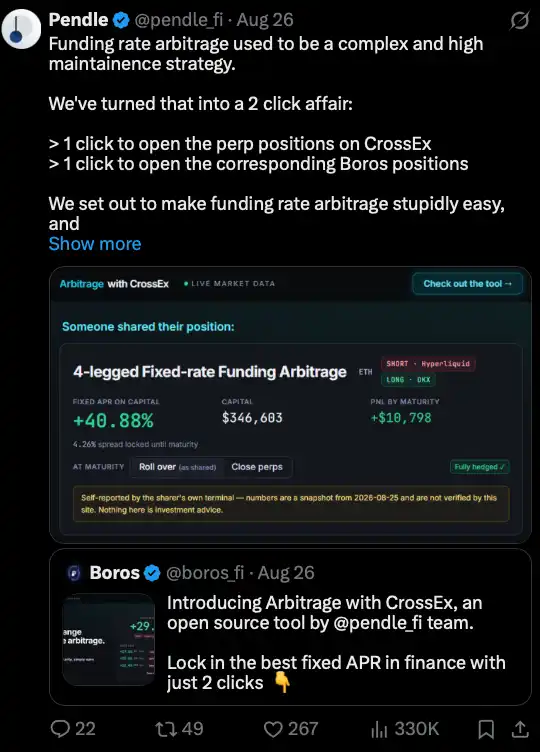
Arbitrage is a product launched by Boros that simplifies cross-platform funding rate arbitrage into a two-click operation.
The arbitrage opportunities currently listed remain attractive, with annualized returns generally ranging from 20% to 40%.
Perpetual futures have become part of the global financial infrastructure, and their scale will only continue to grow.
As funding rates become a ubiquitous financial variable, the market will ultimately need a place to manage, trade, and lock in fixed income from funding rates.
As the perpetual futures wave expands, Pendle will grow with it.
Pendle's Appeal
Yes, these three waves are all very attractive on their own.
But why Pendle specifically?
Simply put, entering Pendle's "maw" means gaining access to top-tier distribution, a complete ecosystem of use cases, and most critically—liquidity.
The aforementioned "Pendle Effect" already demonstrates Pendle's influence in asset distribution.
At the same time, Pendle's PTs have been widely accepted by DeFi and CeFi platforms as collateral and as various DeFi "lego blocks."
Beyond that, we have built cross-chain PTs.
This means PTs can be used as collateral on any supported chain.
Earlier this year, we saw $170 million worth of PT-USDe bridged from Ethereum to BNB Chain and used as collateral.
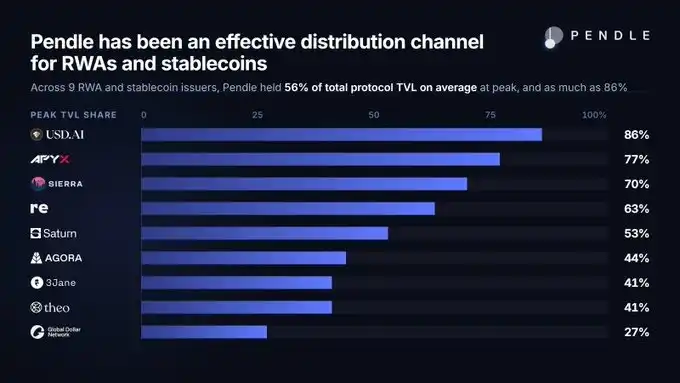
Pendle's role is to continue being the most effective distribution channel for RWAs and stablecoins.
Liquidity Begets More Liquidity
On the liquidity front, we have also completed the hardest infrastructure work.
The current underlying infrastructure is already capable of absorbing the next waves of asset growth at institutional scale.
These systems have been continuously adjusted and upgraded over the past few years and are now ready for deployment.
At the time of writing, users can execute a single $50 million PT-sUSDS swap to lock in an effective fixed APY of about 4.6% with slippage of only -0.05%.
This level of trading efficiency is comparable to the deepest markets on the largest centralized exchanges.
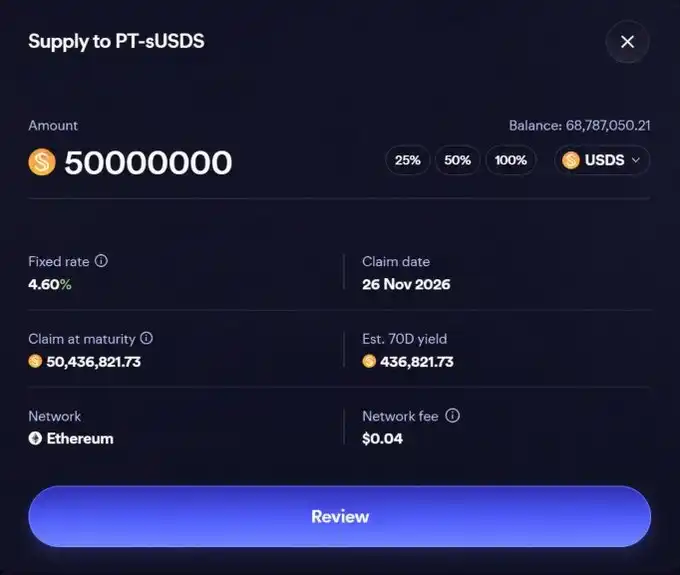
Trade preview for swapping $50 million USDS for fixed yield on Sky via Pendle PT-sUSDS.
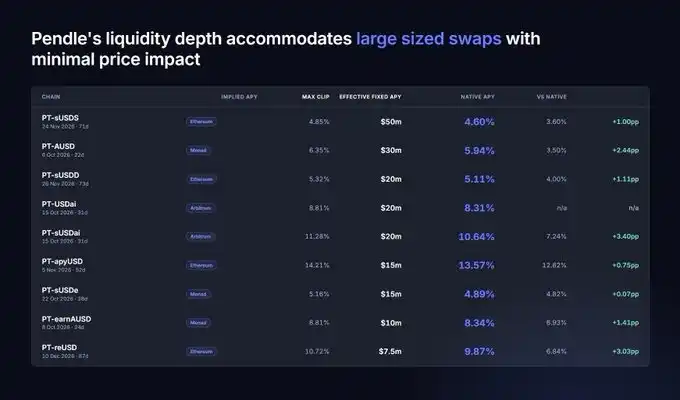
Structures like this "deep trading capacity + fixed-rate premium" are also widely present in Pendle's stablecoin and RWA markets.
Pendle's AMM liquidity is complemented by a limit order system.
Therefore, orders can be partially filled through both the AMM and the limit order system to achieve the best price.
Underlying this system is an algorithmic incentive module called AIM, which automatically designs the allocation strategy for PENDLE rewards across different markets.
AIM is one of our most underrated but impactful improvements in recent years.
Tradable liquidity has grown from about $350 million to about $600 million, up 71% this year.
At the same time, the cost efficiency of acquiring liquidity has improved 22x.
Today, Pendle is more efficient and capable than ever at handling large trades.
Meanwhile, the token incentives it relies on have dropped dramatically—emissions have decreased by 92% since the start of the year.
AUSD is an example of a highly efficient market.
Its floating TVL is currently $130 million, but the AMM actually provides only $2.5 million in liquidity.
This is largely thanks to our limit order system and AIM.
At the time of writing, executing a $20 million trade against this mere $2.5 million pool would impact yield by only 0.22%.
In the past, this would have been almost unimaginable without billions of dollars in TVL.
Does this sound attractive to RWA or stablecoin issuers?
We believe we have presented a fairly compelling answer.
When a mass accumulates past a certain critical point, it begins to reorganize the space around it.
And everything that enters its sphere of influence starts to gravitate toward it.
This structure itself is what makes "choice" gradually lose meaning.
Because this attraction is ultimately inevitable.
A stablecoin that wants to expand needs an effective distribution channel where users can earn yield.
A tokenized fund that goes on-chain with floating rates needs a place to split out the yield.
Perpetual futures on any asset, whether the underlying is on-chain or off-chain, generate funding rates.
And for funding rates to be hedged, there must be a market where funding rates can actually be traded.
The foundation is laid.
The infrastructure is in place.
These three asset classes are all moving toward hyperscale markets.
And in each case, the yield they generate ultimately has only one market deep enough to flow into.
Pendle.
This content is for informational and educational purposes only and does not constitute investment advice related to BTCC. BTCC makes every effort but cannot guarantee the truthfulness, accuracy, or originality of the content above.